Home Improvement Loans for Low Income Homeowners: 2026 Guide
Find home improvement loans for low income homeowners, from USDA grants to deferred payment loans. Call (833)-365-8755 for guidance on your repair funding options.
By Jessica Reis
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
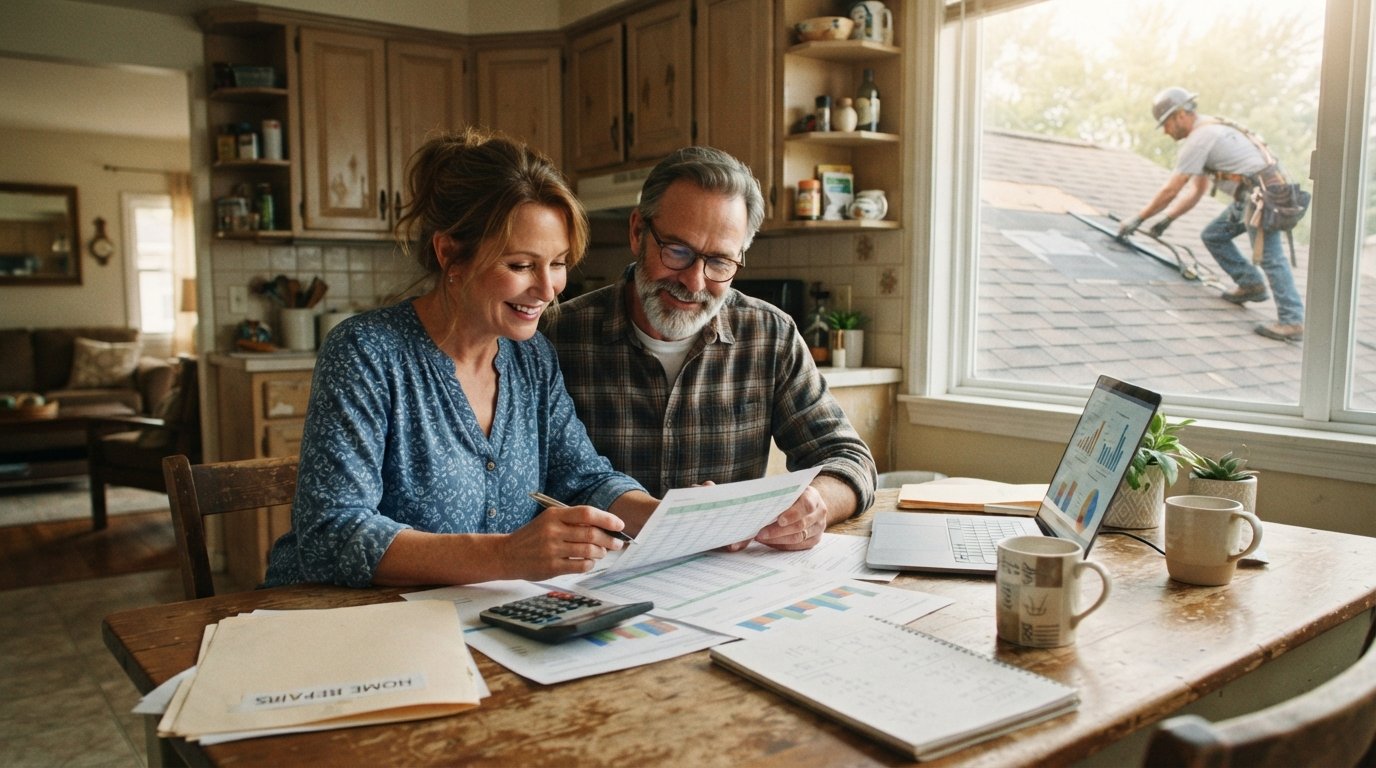
Your roof is leaking, your furnace is failing, or your bathroom is no longer safe to use, but your bank account cannot cover the repair. That is a reality for millions of homeowners living on fixed or modest incomes. The good news is that a wide network of federal, state, local, and nonprofit programs exists specifically to help low income homeowners fund essential repairs and accessibility upgrades. The key is knowing where to look, what each program requires, and how to apply without wasting weeks on dead ends.
Why Traditional Lenders Say No and What Works Instead
Banks and credit unions evaluate loan applications using credit scores, debt to income ratios, and collateral. When your income is low or your credit history is thin, those filters reject you before a human ever reviews your situation. Home improvement loans for low income homeowners work differently because government agencies and nonprofit lenders use different criteria. They focus on whether the repair is necessary, whether you own and occupy the home, and whether your household income falls below a specific threshold.
That does not mean the money is free or easy. Most programs require documentation, patience, and a willingness to work through a process that can take several weeks or months. But the interest rates are often zero or below market, and some assistance comes as a grant that never has to be repaid. Understanding the landscape before you apply saves time and prevents frustration.
Federal Programs That Fund Essential Repairs
The federal government operates several programs designed for homeowners who cannot qualify for conventional financing. Each one targets a different need, from rural housing rehabilitation to urban code compliance.
USDA Section 504 Loans and Grants
The USDA Section 504 program serves homeowners in rural areas who need to repair, improve, or modernize their homes. It offers two tracks: a loan with a 1 percent interest rate and a grant of up to $10,000 for elderly homeowners aged 62 and older who cannot repay a loan. The loan portion can reach $40,000 and must be repaid over 20 years. To qualify, your household income must be below 50 percent of the area median income, and you must be unable to obtain credit elsewhere. The property must be in an eligible rural area, which the USDA defines broadly but excludes many suburban and urban communities.
Applications go through your local USDA Rural Development office. You will need proof of income, property ownership documents, and a description of the repairs. Turnaround times vary by office workload, but expect at least 30 to 60 days from application to approval.
HUD Title I Property Improvement Loans
The HUD Title I program insures loans made by private lenders, which reduces the risk for banks and credit unions. That insurance allows lenders to approve borrowers with lower credit scores and higher debt ratios than they normally would. You can borrow up to $25,000 for a single family home and up to $60,000 for a multifamily property. The loan can cover repairs, improvements, and even some accessibility modifications. Terms run up to 20 years.
Not every lender participates in Title I, so you will need to ask around. Credit unions and community banks are more likely to offer these loans than large national banks. The application process mirrors a standard loan, but the HUD insurance gives you a second chance if your credit profile is borderline.
FHA 203(k) Rehabilitation Loans
The FHA 203(k) program lets you purchase or refinance a home and include the cost of repairs in a single mortgage. It is not limited to low income homeowners, but it is one of the few options that allows you to finance major repairs with a low down payment and a government backed loan. The standard 203(k) covers structural repairs, roofing, plumbing, HVAC, and accessibility upgrades. A streamlined version, called the limited 203(k), caps repairs at $35,000 and covers cosmetic fixes like flooring and paint.
The catch is complexity. You must work with an FHA approved lender and a HUD consultant who inspects the work and releases funds in draws. The process can take 60 to 90 days or longer, and not every contractor is willing to wait for draw payments. Still, for a low income homeowner who needs a new roof and a new furnace, the 203(k) can bundle everything into one affordable payment.
State and Local Housing Agency Programs
Every state operates a housing finance agency that administers repair grants and deferred payment loans. These programs often fly under the radar because they are not advertised nationally, but they can be the fastest path to funding for low income homeowners. A deferred payment loan means you pay nothing until you sell the home, refinance, or transfer the title. At that point, the loan is repaid from the sale proceeds.
Typical state programs offer $10,000 to $50,000 for repairs that address health and safety hazards, code violations, or accessibility needs. Examples include roof replacement, septic system repair, lead paint abatement, and wheelchair ramp installation. Income limits usually range from 50 percent to 80 percent of the area median income, and you must own and occupy the property as your primary residence.
Local governments, including cities and counties, often layer their own programs on top of state offerings. Some use federal Community Development Block Grant funds to provide zero interest loans or grants to low income homeowners in specific neighborhoods. To find these programs, start with your state housing finance agency website, then check your city or county community development department. A phone call to your local housing authority can uncover programs that are not well publicized online.
Weatherization and Energy Efficiency Assistance
The Weatherization Assistance Program, funded by the U.S. Department of Energy, helps low income households reduce energy costs by improving insulation, sealing air leaks, and upgrading heating and cooling systems. Unlike a loan, this is a grant that does not require repayment. Income eligibility typically caps at 200 percent of the federal poverty level, though some states set higher limits.
Weatherization crews perform an energy audit, then complete the work at no cost to you. Typical improvements include attic insulation, duct sealing, furnace repair or replacement, and air sealing around windows and doors. The program prioritizes elderly residents, people with disabilities, and families with young children. Waitlists can be long, so apply early if you qualify.
Utility companies also offer low income energy efficiency programs. Many utilities provide free or subsidized upgrades, such as LED bulbs, smart thermostats, and water heater blankets. Some offer rebates for furnace or air conditioner replacement. Check with your utility provider and your state energy office to see what is available in your area.
Nonprofit and CDFI Repair Programs
Community development financial institutions, or CDFIs, are mission driven lenders that serve borrowers who fall outside mainstream banking. Many CDFIs offer home repair loans with below market interest rates, flexible underwriting, and counseling to help you succeed. Some operate as nonprofits and provide grants for emergency repairs, such as a failed water heater or a leaking roof.
Habitat for Humanity operates a repair program in many chapters that serves low income homeowners with critical repairs, accessibility modifications, and exterior maintenance. Rebuilding Together is another national nonprofit that mobilizes volunteers and funds to repair homes for veterans, seniors, and low income families. These programs often combine volunteer labor with donated materials, which stretches every dollar further.
To find CDFIs and nonprofit programs in your area, visit the CDFI Coalition website or call 211, a national referral service that connects callers with local resources. When you contact a nonprofit, ask about eligibility, application requirements, and whether they offer grants or only loans. Some programs require you to attend homeowner counseling or complete a budget workshop before receiving funds.
If you want to compare contractor bids for your repair project before you apply for funding, a home improvement quote tool can help you gather multiple estimates in one place. Having three written quotes strengthens your application and ensures you are not overpaying for the work.
How to Apply: Documents, Timelines, and Practical Steps
Most repair assistance programs require a similar set of documents. Gathering them before you apply speeds up the process and reduces the chance of delays. You will typically need proof of income for all household members, such as pay stubs, Social Security award letters, or tax returns. You will also need proof of ownership, such as a deed or property tax bill, and a government issued photo ID. Some programs require a written scope of work from a licensed contractor, so you may need to obtain bids before you apply.
Here is a practical sequence to follow when pursuing home improvement loans for low income homeowners:
- Identify the repairs you need and separate essential health and safety items from cosmetic upgrades.
- Contact your state housing finance agency, local housing authority, and 211 to map out available programs.
- Gather your income, ownership, and identity documents before you start any application.
- Obtain at least two written contractor estimates for the work, so you can document the cost.
- Submit applications to every program you qualify for, and follow up regularly to check status.
Turnaround times vary widely. Emergency repair programs may respond within a few weeks, while deferred payment loans and federal programs can take two to six months. Weatherization programs often have waiting lists that stretch six months to a year. Apply as early as possible, and keep copies of everything you submit. If one program denies you, ask why and whether they can refer you to another resource.
It also helps to understand the difference between a grant and a loan before you sign anything. A grant does not need to be repaid. A deferred payment loan accrues no interest and requires no monthly payment, but the balance comes due when you sell or transfer the home. A low interest loan requires monthly payments, which may strain a fixed income. Read the terms carefully and ask a housing counselor to review the documents if anything is unclear.
For homeowners who want to explore remodeling ideas that fit a tight budget, resources like PlanRemodel offer directories of pre-vetted contractors and educational guides that can help you plan a cost effective project. Pairing a solid repair plan with the right funding program gives you the best chance of completing the work without falling into debt.
Finally, do not overlook the importance of contractor vetting. A low cost loan will not help if the contractor does poor work or disappears with your deposit. Verify licenses, check references, and insist on a written contract that spells out the scope, timeline, and payment schedule. If a program provides a list of approved contractors, use it. Those contractors have already been screened for insurance and licensing, which reduces your risk.
Low income homeowners have more options than they often realize. The combination of federal programs, state and local grants, weatherization assistance, and nonprofit repair programs creates a safety net for essential repairs. The process takes patience and paperwork, but the result is a safer, more energy efficient home that you can afford to keep. Start with a clear list of your repair needs, make a few phone calls, and apply to every program that fits. The help is there if you know where to find it.