How to Structure Contractor Payments with a Draw Schedule
Structure contractor payments with a draw schedule to protect your budget and ensure quality work. Call (833)-365-8755 for expert guidance.
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Handing over a large deposit before a single nail is hammered is one of the fastest ways to lose leverage on a renovation project. Yet many homeowners do exactly that because they do not know how to structure contractor payments with a draw schedule. A draw schedule ties money to completed work, protects your budget, and keeps the project moving without putting your funds at risk. This guide walks you through the mechanics of milestone-based payments, retainage, lien waivers, and the red flags that should make you pause before signing a contract. Whether you are remodeling a kitchen, replacing a roof, or finishing a basement, the payment structure you agree to at the outset will shape the entire project experience.
What a Draw Schedule Is and Why It Matters
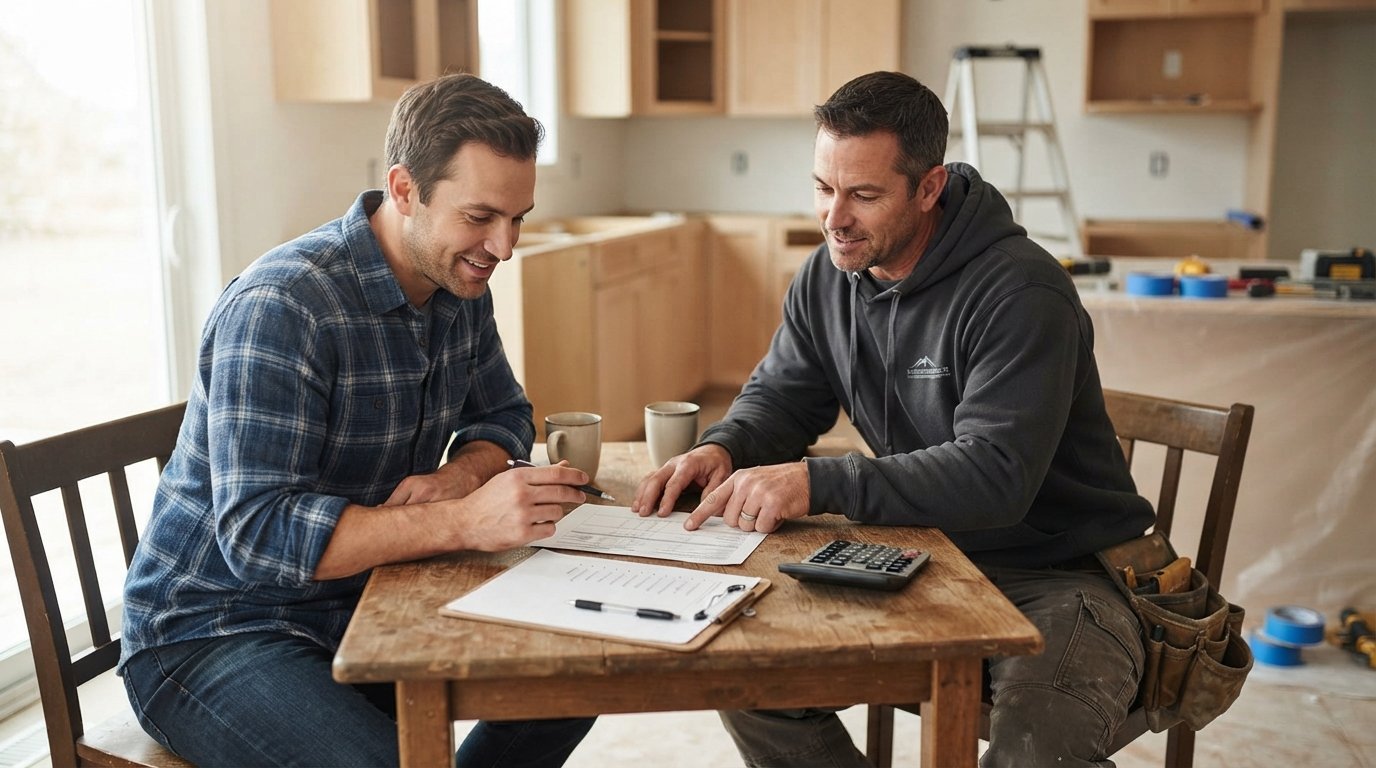
A draw schedule is a written plan that breaks the total contract price into a series of payments, called draws, each released when a specific phase of work is completed and verified. Instead of paying a lump sum upfront or at the end, you pay as the project progresses. This approach aligns the contractor's cash flow with actual progress and gives you a built-in checkpoint at every stage. It is the single most effective tool a homeowner has for managing financial risk during a renovation.
The alternative, often called a front-loaded schedule, concentrates payments early in the project. Contractors may request a large deposit to cover materials and mobilization, but when that deposit balloons to 30 or 50 percent of the contract, your leverage evaporates. If the contractor walks away or performs substandard work, recovering your money becomes a legal battle. A well-designed draw schedule prevents that scenario by keeping the bulk of the money in your account until the corresponding work is done. For a deeper look at the mechanics, see our guide on what a construction draw schedule is and how it works.
A draw schedule also benefits the contractor. It provides predictable cash flow, reduces the need for expensive short-term financing, and demonstrates to subcontractors and suppliers that the project is professionally managed. When both parties understand the schedule, disputes over payment timing become far less common.
Building a Milestone-Based Payment Schedule
The foundation of any draw schedule is a clear list of milestones. Each milestone should represent a meaningful, verifiable unit of work, not a vague percentage like "30 percent complete." For a bathroom remodel, milestones might include demolition and rough-in plumbing, drywall and waterproofing, tile installation, fixture installation, and final punch list. For a roof replacement, milestones could be tear-off and deck inspection, underlayment and flashing, shingle installation, and final cleanup and inspection.
Once you have defined the milestones, assign a dollar amount or percentage to each. A common approach is to tie each draw to the cost of labor and materials for that phase, plus a reasonable overhead and profit margin. The first draw should be modest, often 10 percent or less, and should be tied to mobilization and initial material delivery, not simply to signing the contract. The final draw should be large enough to ensure the contractor returns to complete punch-list items, typically 10 to 15 percent of the total price.
Here is a sample structure for a $60,000 kitchen remodel:
- Draw 1 (10 percent, $6,000): Mobilization, permits, and initial material delivery.
- Draw 2 (25 percent, $15,000): Demolition and rough framing complete.
- Draw 3 (25 percent, $15,000): Electrical, plumbing, and HVAC rough-in inspected and approved.
- Draw 4 (20 percent, $12,000): Drywall, cabinetry installation, and countertop template complete.
- Draw 5 (10 percent, $6,000): Countertops installed, flooring and fixtures complete.
- Final Draw (10 percent, $6,000): Punch list complete, final inspection passed, and lien waivers collected.
This structure keeps the largest payments tied to phases that are easy to inspect and verify. It also ensures the contractor has a financial incentive to finish strong. Adjust the percentages to fit your project, but keep the principle intact: money follows work, not promises.
The Role of Retainage and Final Payment
Retainage is a portion of each payment, or a lump sum at the end, held back until the project is fully complete. In residential construction, retainage of 5 to 10 percent is common, but for homeowner protection, a final payment of 10 to 15 percent held until punch list completion is more typical. The purpose is simple: it gives the contractor a reason to return for touch-ups, final inspections, and warranty documentation. Without a meaningful final payment, small issues can linger for months.
Define what "complete" means in the contract. It should include passing final inspections, delivering all warranties and manuals, removing debris, and providing lien waivers from subcontractors and suppliers. The final payment should only be released after you have walked the project, verified every item on the punch list, and received the necessary paperwork. Some homeowners also hold a small amount for a short warranty period, but this is less common in residential projects and should be negotiated carefully.
Retainage also protects you if a subcontractor files a mechanics lien. If the general contractor has not paid a supplier, that supplier can place a lien on your property even if you have paid the general contractor in full. By holding back final funds and requiring lien waivers, you create a paper trail that discourages this outcome. Always make the final payment contingent on receiving conditional lien waivers for the current payment and unconditional waivers for all prior payments.
Mechanics Liens, Waivers, and Receipt Documentation
A mechanics lien is a legal claim against your property by a party who has not been paid for work or materials. In many states, subcontractors and suppliers can file a lien even if you have no direct contract with them. This is why lien waivers are essential. A lien waiver is a document in which a contractor or supplier gives up the right to file a lien in exchange for payment. There are two main types: conditional waivers, which become effective only when payment clears, and unconditional waivers, which are effective immediately upon signing.
For each draw, request a conditional lien waiver from the general contractor and from any subcontractors or suppliers who have provided work or materials for that phase. Once the payment clears, those conditional waivers convert to unconditional waivers for that amount. Keep a file with every waiver, along with receipts for materials delivered to your property. If a supplier later claims nonpayment, your documentation will show that the materials were paid for. This is especially important on larger projects where multiple trades are involved.
Receipt documentation also helps you verify that your draws are being used as intended. Ask for invoices or receipts for major materials, such as cabinets, windows, or roofing shingles, before releasing the corresponding draw. This practice prevents the contractor from using your funds for other projects and ensures that materials are actually ordered and delivered. It is a simple step that adds a layer of accountability without adding much administrative burden.
Red Flags: Large Deposits and Payments Before Delivery
One of the most common mistakes homeowners make is agreeing to a large upfront deposit. A request for 30 percent or more before any work begins is a red flag, especially if the contractor cannot provide a detailed breakdown of what the deposit covers. Legitimate contractors may ask for a deposit to cover permits and initial materials, but it should be modest and tied to specific costs. If the contractor demands a large sum in cash or before providing a written contract, walk away.
Another red flag is being asked to pay for materials before they are delivered to your site. Some contractors may request a draw for materials that are still at the supplier or in transit. Always verify delivery before releasing funds. Similarly, be wary of contractors who ask you to pay subcontractors directly or who cannot provide lien waivers. These practices can leave you exposed to liens and disputes. A professional contractor will have no problem with a milestone-based schedule, retainage, and lien waiver requirements. In fact, they will appreciate the clarity.
Finally, never pay in cash without a receipt, and never pay for work that has not been inspected and approved. If a contractor pressures you to release a draw before a milestone is complete, hold firm. The schedule you agreed to is your protection, and any attempt to circumvent it is a warning sign.
Putting It All Together: A Step-by-Step Process
Structuring contractor payments with a draw schedule requires preparation before the contract is signed. Start by defining the scope of work in detail, then break it into milestones. Assign a dollar amount to each milestone and decide on a retainage amount. Next, draft the payment terms in the contract, including the requirement for lien waivers and receipts. Once the project begins, inspect each milestone before releasing the corresponding draw, and keep meticulous records. If you need help finding a contractor who is comfortable with this approach, you can request free quotes from licensed professionals who understand draw schedules.
For homeowners exploring energy-efficient upgrades, such as solar panel installation, the same payment principles apply. You can also explore resources like FreeSolarPowerQuotes to compare solar options and incentives, but always apply the same draw schedule discipline to any contractor agreement. The key is to never release funds before you have verified the work and the paperwork.
By following these steps, you can protect your investment and ensure a smoother renovation experience. A draw schedule is not just a payment plan; it is a risk management tool that keeps everyone accountable.